
How Much Does COBRA Insurance Cost?
Updated on | Written by Alec Pow
This article was researched using 13 sources. See our methodology and corrections policy.
COBRA continuation coverage does not have one national premium, because your price is tied to the full cost of your employer’s group health plan. KFF’s 2025 employer-plan benchmark reports average annual premiums of $9,325 for single coverage and $26,993 for family coverage, while the Department of Labor says standard COBRA can charge up to 102% of plan cost.
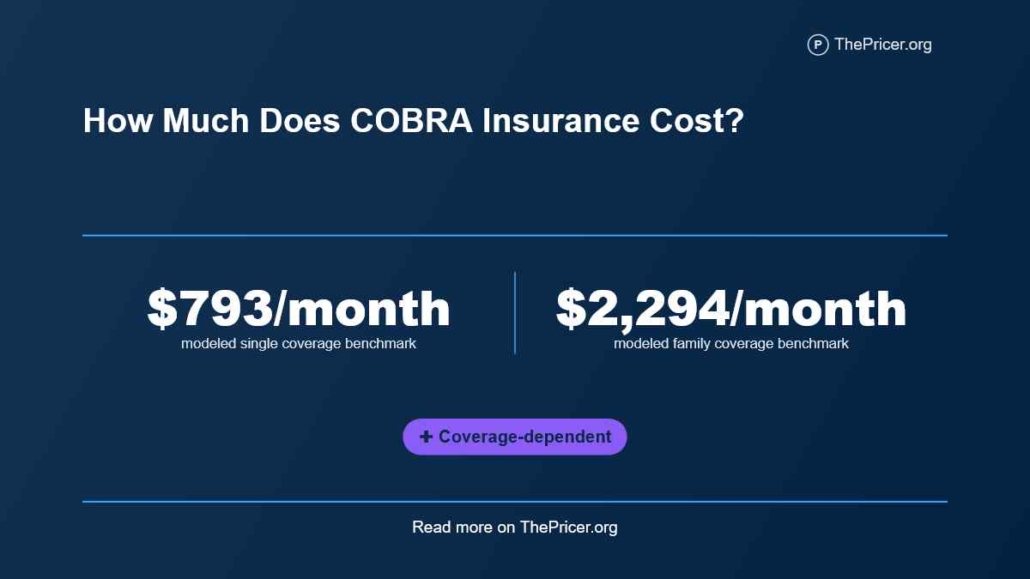
Applying that rule produces a modeled cost of about $793 per month for average single coverage and $2,294 per month for average family coverage. Your actual bill can be lower or higher. The largest change for many workers is losing the employer contribution that previously paid much of the group premium.
Article Highlights
Jump to sections
- A current modeled benchmark is about $793 (at $30 per hour, earning that amount would take about 3.3 full-time workdays, before taxes) per month for single COBRA coverage and $2,294 per month for family coverage.
- Federal COBRA can charge up to 102% of the total plan cost during the standard continuation period.
- The average 2025 worker paid only $120 per month toward single employer coverage and about $571 per month toward family coverage before COBRA.
- A qualifying disability extension can allow a premium as high as 150% of the plan cost for months 19 through 29 when the disabled beneficiary remains covered.
- Job loss can create a Marketplace Special Enrollment Period even when the employee quit or was fired.
- COBRA does not extend the Medicare Part B Special Enrollment Period that follows the end of current employment.
How Much Does COBRA Insurance Cost?
KFF’s 2025 employer-plan survey puts average annual premiums at $9,325 (about 7.8 full-time workweeks at $30 per hour) for single coverage and $26,993 for family coverage, with workers contributing $1,440 and $6,850 on average. It also reports HDHP with savings-option premiums of $8,620 single and $25,379 family, compared with PPO premiums of $9,818 single and $28,272 family. Using the 102% standard COBRA cap described above produces the modeled values below.
| 2025 employer-plan benchmark | Annual plan premium | Modeled 102% COBRA per month |
|---|---|---|
| Average single coverage | $9,325 | $793 |
| Average family coverage | $26,993 | $2,294 |
| HDHP with savings option, single | $8,620 | $733 |
| HDHP with savings option, family | $25,379 | $2,157 |
| PPO, single | $9,818 | $835 |
| PPO, family | $28,272 | $2,403 |
The spread shows why a flat national COBRA price is misleading. The same 102% rule can produce different bills because the underlying group plan costs differ. A PPO family benchmark is about $246 per month above the HDHP family benchmark in this calculation.
The plan’s own current premium is the number that controls your actual election notice. The same plan can become more expensive when its underlying premium rises for the next determination period.
What COBRA Keeps
COBRA is a federal continuation right, not a new insurance product. It can let a qualified worker, spouse, former spouse, or dependent child keep group health coverage after a qualifying event causes that coverage to end. The continuation coverage must match the coverage offered to similarly situated active participants.
That means the same plan rules can continue, including deductibles, copays, coverage limits, claim procedures, and open-enrollment choices. Changes made for similarly situated active workers can also carry over to COBRA participants during the continuation period.
This continuity can have real financial value even when the premium is high. Someone in the middle of treatment may already have met much of an annual deductible, have specialists inside the existing network, or rely on a drug formulary that works well for current prescriptions. Moving to a different plan can change all three.
The protection is temporary. It exists to extend a group plan after specific job or family events, not to create permanent individual insurance. That distinction matters because price comparisons should use the same doctors, benefits, deductible position, and coverage period rather than comparing monthly premiums alone.
Why Your Payment Jumps
The 2% administrative allowance is small compared with the employer contribution that can disappear after employment ends. KFF found that workers paid an average of $1,440 (about 1.2 full-time workweeks at $30 per hour) per year, or $120 per month, toward single coverage in 2025. The average family worker contribution was $6,850 per year, or about $571 per month. The rest of the group premium was paid by the employer on average.
Using the same KFF average single plan, standard COBRA at 102% models to about $793 per month. That is $673 more per month than the average worker contribution while employed. Across six months, the modeled COBRA premium is about $4,756, compared with $720 in former payroll contributions over six months. The difference is about $4,036. This is a calculated scenario using national employer-plan averages, not a prediction for one worker.
The family gap is larger in dollars. A modeled 102% family COBRA premium is about $2,294 per month, compared with the average employee contribution of roughly $571 per month. Twelve months of modeled COBRA total about $27,533, which is roughly $20,683 above the average 2025 worker family contribution of $6,850.
The Hidden 150% Extension
The standard 102% cap is not the highest premium allowed under every COBRA situation. The Department of Labor’s disability-extension rules can extend an 18-month continuation period by 11 months, creating a maximum of 29 months. During that extension, a plan may charge up to 150% of the cost of coverage when the disabled qualified beneficiary remains covered. This is one of the most consequential COBRA price rules because the premium can rise during months 19 through 29.
Using the KFF average single-plan premium as a benchmark, 150% works out to about $1,166 per month. That is about $373 per month above the modeled standard 102% amount. Across an 11-month extension, the difference is about $4,103. Applying the same math to the family benchmark gives about $3,374 per month at 150%, roughly $1,080 per month above the 102% family benchmark, or nearly $11,877 across 11 months.
Those figures illustrate the rule rather than setting a national disability-extension premium. The actual calculation uses the employer plan’s applicable cost. The disability extension also has Social Security Administration timing and notice requirements, so a beneficiary should use the plan’s Summary Plan Description and election notice for the procedure that applies to that plan.
Who Qualifies
Under the Department of Labor’s federal eligibility rules, COBRA applies to qualifying private-sector plans of employers with at least 20 employees on more than half of typical business days in the previous calendar year and to state and local government plans, while qualifying events include job loss other than gross misconduct, reduced hours, divorce or legal separation, death of the covered employee, and loss of dependent status, with termination or reduced hours commonly allowing up to 18 months and specified family events allowing up to 36 months.
Quitting a job does not automatically eliminate eligibility. The key question is whether the event is one recognized by the law and causes the qualified beneficiary to lose the group coverage. The federal employer-size test also counts part-time employees fractionally, so a simple headcount of full-time staff can produce the wrong answer about whether a plan falls under federal COBRA.
The duration depends on the beneficiary and event. The 29-month disability path is a separate extension with its own notice conditions and possible premium increase. A spouse or dependent may have a longer continuation right than the former employee after a later qualifying event. The election notice and Summary Plan Description should identify the period that applies to the household rather than assuming every COBRA case ends after 18 months.
Election and Payment Rules
CMS COBRA timing rules state that an employer normally has 30 days to notify the plan administrator after termination or reduced hours, the administrator normally has 14 days after notice to send election rights, an employer that is also the administrator can have 44 days, each qualified beneficiary gets at least 60 days to elect, the first premium cannot be required before 45 days after election, and later premiums receive the required 30-day payment window.
The first payment can be much larger than one monthly premium because COBRA coverage can be retroactive to the earlier loss of group coverage when the beneficiary elects and pays within the permitted deadlines. Someone who waits near the end of the election period may need to fund several months at once. At the modeled single benchmark of $793 per month, three retroactive months would require about $2,379 at the first payment.
The due date for later premiums comes from the plan. A beneficiary should use the election notice for the exact amount, payment address, and schedule rather than assuming every plan bills on the first day of the month. Missing the permitted payment window can end continuation coverage before the maximum 18, 29, or 36-month period is reached.
Marketplace and Medicare
COBRA is not the only route after job-based coverage ends. HealthCare.gov says losing employer coverage after leaving a job for any reason can create a Marketplace Special Enrollment Period. A Marketplace plan can have a different network, deductible, formulary, and premium, and income-based savings may change what the household pays. Current ACA pricing is covered separately in ACA health insurance costs.
There is a timing trap after COBRA has already been elected. HealthCare.gov states that voluntarily dropping COBRA early does not by itself create a new Marketplace enrollment right. COBRA expiration does create a 60-day Marketplace Special Enrollment Period. Someone still inside the original job-loss enrollment window may have a different path, so the calendar matters before COBRA is canceled.
 Medicare creates a separate deadline. Medicare says the 8-month Part B Special Enrollment Period begins when current employment or job-based coverage ends, even if the person chooses COBRA. COBRA does not extend that clock. People approaching 65 can compare this issue with the broader age 62 to 65 insurance costs before relying on COBRA as a bridge. Coverage start dates should be matched before one plan is ended so that a premium comparison does not create an accidental gap.
When COBRA Fits
The cheapest premium is not always the lowest-cost choice for a household already using care. COBRA may preserve doctors, a hospital system, prescription coverage, prior authorization work, and progress toward the existing deductible or out-of-pocket limit. A Marketplace plan may have a much lower premium after tax credits yet restart cost sharing under a different plan. Comparing both requires the expected remaining medical spending, not just the next monthly bill.
Makes sense if
- You need the existing provider network during active treatment.
- You have already paid a large share of the current plan’s deductible or out-of-pocket limit.
- Your former employer is subsidizing part of the COBRA premium.
- You need a short bridge to another employer plan and the current benefits fit your care.
Does not make sense if
- A Marketplace or spouse plan provides suitable coverage at a much lower total cost.
- You would pay a high COBRA premium mainly to preserve benefits you are unlikely to use.
- You are Medicare-eligible and would delay Part B solely because COBRA remains available.
- You have not compared the provider network, prescriptions, deductible, and out-of-pocket exposure of the alternatives.
A useful comparison puts each option on the same time period. For a six-month bridge, compare six months of premiums plus realistic medical cost sharing under COBRA against six months under the alternative plan. Readers comparing Marketplace options can also use the related Obamacare cost analysis for premium and subsidy context.
Verification
- Checked the Department of Labor’s election notice requirements for required notice content.
- Confirmed the Department of Labor’s COBRA disclosure schedule for administrator timing.
- Cross-referenced CMS public-sector COBRA jurisdiction for state and local government plans.
Answers to Common Questions
How much does COBRA cost per month?
The actual premium depends on the employer plan. Using 2025 national employer-plan averages and the standard 102% COBRA maximum gives a benchmark of about $793 per month for single coverage and $2,294 per month for family coverage.
Why is COBRA so much more expensive than my old payroll deduction?
The employer usually paid part of the group premium while you were employed. COBRA can shift nearly the entire plan premium to you, plus the permitted administrative amount.
Can I choose a Marketplace plan instead of COBRA?
Yes, losing job-based coverage can create a Marketplace Special Enrollment Period. Compare premiums, tax-credit eligibility, networks, prescriptions, deductibles, and expected care costs before choosing.
Can I wait until COBRA ends to enroll in Medicare Part B?
That can create a problem. COBRA does not extend the 8-month Part B Special Enrollment Period that follows the end of current employment or job-based coverage.
Disclosure: Educational content, not medical advice. Pricing varies by provider, location, and insurance. Confirm eligibility, coverage, and out-of-pocket costs with a licensed clinician and your insurer. See our methodology and corrections policy.