
How Much Is Anthropic Worth?
Published on | Written by Alec Pow
This article was researched using 13 sources. See our methodology and corrections policy.
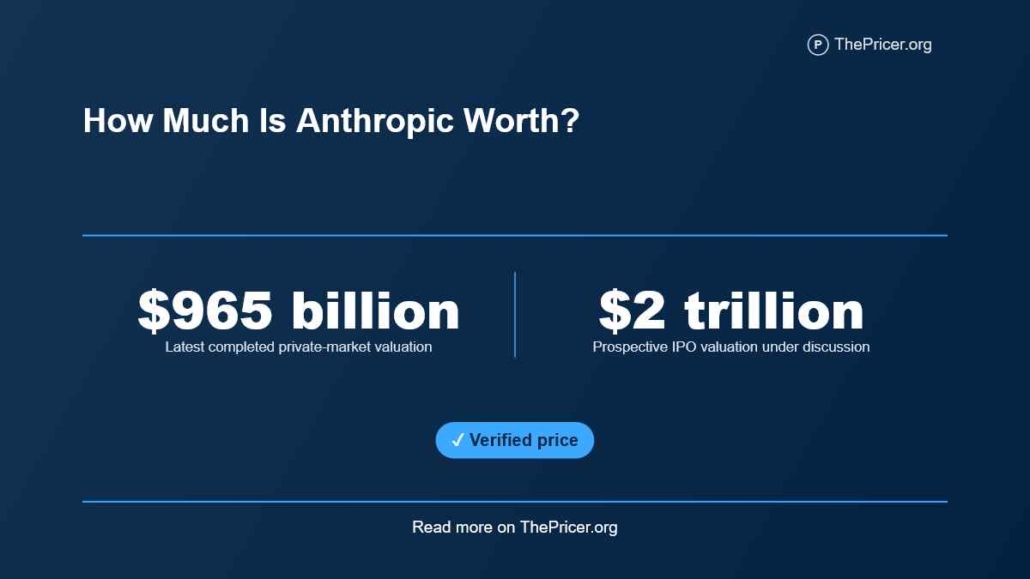
Anthropic’s latest completed financing valued the Claude maker at $965 billion post-money, but the number now shaping the market is much larger. Reuters reports that Anthropic is discussing an IPO that could value the company near $2 trillion and raise as much as $100 billion. That prospective price would arrive while Anthropic’s annualized revenue run rate has climbed above $65 billion.
The valuation question is really a growth question. At the current run rate, $2 trillion equals about 30.8 times revenue. If Anthropic reaches roughly $100 billion of annualized revenue, the multiple falls near 20 times. If its $190 billion to $200 billion 2028 forecast proves accurate, the same valuation falls near 10 times revenue. The debate is about how much future growth investors should pay for today.
Article Highlights
Jump to sections
- Anthropic’s latest completed funding round valued the company at $965 billion (at $30 per hour, earning that amount would take about 15.5 million years of full-time work, before taxes).
- A possible IPO has been discussed at roughly $2 trillion, but that is not a completed valuation.
- Annualized revenue run rate exceeded $65 billion by the end of July 2026.
- The current private valuation equals about 14.8 times that latest run rate.
- A $2 trillion valuation would equal about 30.8 times the same run rate.
- Anthropic would need roughly $97.4 billion of annualized revenue for $2 trillion to carry the same revenue multiple investors paid in May.
How Much Is Anthropic Worth?
Anthropic’s latest established private-market value is $965 billion (about 15.5 million years of full-time work at $30 per hour). The company raised $65 billion in Series H on May 28, 2026, at that post-money valuation and said its revenue run rate had crossed $47 billion earlier that month. Post-money means the stated value includes the new capital added in the round. It is the strongest current answer to the question because investors actually bought into the company at that price.
The $2 trillion number belongs in a different category. Reuters reports that Anthropic is preparing a possible public offering that could raise as much as $100 billion and value the company around $2 trillion at the IPO. Nvidia has discussed an anchor investment of up to $10 billion. Those terms remain prospective and can change before shares are sold to the public.
The distinction matters. Anthropic’s February financing valued it at $380 billion, followed only three months later by the $965 billion May round. A $2 trillion IPO would more than double the equity value again. That sounds extreme until revenue growth is placed beside it directly.
What a $2 Trillion IPO Means
A public offering near $2 trillion (about 32 million years of full-time work at $30 per hour) would do something the private rounds cannot. It would expose Anthropic’s valuation to a much larger market of institutional and public investors while forcing far greater financial disclosure. The price would no longer rest mainly on negotiations among private funds, strategic backers and the company. Public investors would be able to compare revenue, expenses, cash flow, customer concentration and contractual obligations in a formal filing.
The size of the proposed raise matters too. A $100 billion offering would provide a huge pool of capital for compute, hiring and product expansion, but dilution depends on the final share structure and primary versus secondary stock sold. A $2 trillion market value also would not mean Anthropic receives $2 trillion in cash. It would mean the market places that value on all outstanding equity at the offering price.
There is another reason the IPO price deserves caution. The private valuation already incorporates large expectations about future revenue. Moving from $965 billion to $2 trillion would more than double the equity value again. Investors need either a much higher revenue base, stronger profit economics, or both. The IPO becomes less a judgment about Claude today than a wager on what Anthropic looks like two or three years from now.
Revenue Is Catching Up
Anthropic’s revenue growth is the strongest argument against treating the valuation jump as pure hype. In February, the company reported a $14 billion run rate alongside its $380 billion Series G valuation. By April, run-rate revenue was above $30 billion, and more than 1,000 business customers were each spending over $1 million on an annualized basis. In May, the run rate crossed $47 billion. Reuters later reported that annualized revenue run rate had exceeded $65 billion by the end of July.
That progression changes the multiple quickly. The February funding valued Anthropic at about 27.1 times its then-current run rate. The May round valued it at about 20.5 times the $47 billion run rate disclosed that month. Using the later $65 billion run rate against the same $965 billion valuation reduces the multiple to about 14.8 times.
The company also disclosed that Claude Code had surpassed $2.5 billion in run-rate revenue in February, with enterprise use representing more than half of that product’s revenue. Anthropic said more than 500 customers were spending over $1 million annually at that point. The valuation is rising fast. Revenue has, at several points, risen even faster.
Run Rate Is Not Revenue
 The $65 billion figure needs careful wording. It is annualized revenue run rate, not a statement that Anthropic collected $65 billion during the prior twelve months. Run rate extrapolates the latest sales pace across a full year. That can be useful for a company growing this quickly because trailing revenue can become stale within a few months. It can also make the business look larger than the amount already booked.
Financial Times reporting based on investor materials said Anthropic generated about $11.5 billion of Q2 revenue. That is a different measure. It describes revenue for a completed quarter rather than extrapolating a recent monthly pace. The same reporting said annualized revenue had reached $65 billion by July, could reach roughly $120 billion by year-end, and was expected to produce positive adjusted operating income for a second consecutive quarter. The adjusted measure excludes stock-based compensation. Reported gross margins above 80% were before revenue sharing and model-training costs.
That distinction should stay attached to every valuation multiple in this piece. Dividing $2 trillion by $65 billion produces a valid run-rate multiple of 30.8 times. It does not produce a trailing-twelve-month revenue multiple. Anthropic’s eventual IPO filing should give investors a cleaner set of reported periods and accounting definitions. Until then, fast-moving run-rate numbers are useful signals with an important limit.
The Case for $2 Trillion
The bull case starts with enterprise adoption. Anthropic is selling Claude into coding, finance, research and other business workflows where customers can spend far more than a consumer subscription. More than 100,000 customers already use Claude through Amazon Bedrock, and Anthropic has committed more than $100 billion to AWS technologies over ten years while securing up to 5 gigawatts of added capacity. That spending would be reckless without a belief that demand will remain very large.
Profitability evidence has improved too, but the accounting labels keep the claim narrower than a normal statement that the company is profitable. Positive adjusted operating income and high pre-adjustment gross margins suggest operating efficiency is improving. Public investors will still want GAAP earnings, cash-flow figures and the costs excluded from those measures before deciding how much of the revenue growth converts into durable profit.
The biggest defense of $2 trillion is the denominator investors may be using. Reuters reports that bankers are looking at projected $190 billion to $200 billion of 2028 revenue. At those figures, a $2 trillion valuation equals about 10.0 to 10.5 times revenue. That is still rich, but it is very different from 30.8 times the latest run rate.
| Valuation case | Revenue basis | Implied revenue multiple |
|---|---|---|
| $380 billion February round | $14 billion run rate | 27.1× |
| $965 billion May round | $47 billion run rate | 20.5× |
| $965 billion May value | $65 billion July run rate | 14.8× |
| $2 trillion IPO case | $65 billion July run rate | 30.8× |
| $2 trillion IPO case | $100 billion run rate | 20.0× |
| $2 trillion IPO case | $190 billion to $200 billion 2028 revenue | 10.0× to 10.5× |
Compute Is the Hidden Bill
Anthropic’s growth is expensive because every new wave of Claude usage requires computing capacity. The company trains and serves models across AWS Trainium, Google TPUs and Nvidia GPUs. That infrastructure diversity can lower dependency on one chip supplier, but it does not make the hardware cheap. The economics behind Nvidia H200 hardware costs show why frontier AI companies can absorb enormous capital even before data-center construction and electricity are counted.
Cloud commitments expose the scale. The Amazon agreement exceeds $100 billion over ten years, while Anthropic has also arranged multiple gigawatts of TPU capacity with Google and Broadcom. Data centers then need electrical equipment, cooling and ongoing power. Large AI campuses can carry substantial AI data center cooling costs before model-training or inference hardware is included.
This is why an 80% gross-margin headline needs its qualification. If revenue sharing and model-training costs sit outside the quoted measure, public investors still need to see the fully loaded economics. They will want to know how much incremental revenue survives inference, training, depreciation, cloud contracts and customer acquisition. Cheaper models also create pricing pressure. The economics of GPT-6 Astra API pricing show how quickly frontier-model pricing can become a competitive weapon.
Is Anthropic an AI Bubble?
The bubble case begins with how far forward investors must look. A $2 trillion valuation against the current $65 billion run rate is 30.8 times revenue. Reuters reports that bankers are leaning heavily on 2028 sales forecasts, a farther-forward approach than investors usually use when pricing an IPO. That makes the valuation unusually dependent on growth that has not happened yet.
The bull case
Anthropic’s growth has repeatedly outrun its valuation multiple. Run-rate revenue rose from about $9 billion at the end of 2025 to more than $65 billion by the end of July, a 7.2-fold increase in roughly seven months. Customer spending is moving deeper into enterprise accounts, Claude Code has become a multibillion-dollar product on a run-rate basis, and adjusted operating income has turned positive under the company’s preferred measure. If annualized revenue reaches around $100 billion, much of the apparent multiple expansion disappears.
The bubble case
The capital loop is harder to ignore. Some of Anthropic’s largest infrastructure suppliers are also investors in the company. Reuters Breakingviews has highlighted the circular financial ties across the AI sector, including Amazon’s stake in Anthropic alongside large AWS spending commitments. These relationships do not make Anthropic’s customer revenue fictitious. They do make it harder to separate pure software demand from a capital cycle in which suppliers, investors and customers can overlap.
A second risk comes from Anthropic itself. CEO Dario Amodei has called for frontier labs to slow model capability development while safety work catches up. The timing is unusual for a company preparing one of history’s largest IPOs. A slower model race could cut compute spending and reduce some product-launch velocity. It could also protect established leaders by raising the cost of safety work for smaller rivals. The financial effect is not one-directional.
What Has to Go Right?
The cleanest way to judge $2 trillion is to ask what revenue level makes that valuation resemble the deal investors already accepted. In May, $965 billion divided by the company’s $47 billion run rate produced a multiple of about 20.5 times. Holding that multiple constant, a $2 trillion valuation requires about $97.4 billion in annualized revenue. That is the central threshold.
Worked $2 trillion valuation test
- May valuation was $965 billion.
- May revenue run rate was $47 billion.
- The implied May multiple was about 20.5 times revenue.
- $2 trillion divided by 20.5 requires about $97.4 billion in annualized revenue.
- This comparison does not adjust for profit margins, dilution, cash raised or a change in public-market risk appetite.
That threshold is much closer than the headline valuation suggests. If Anthropic reaches $100 billion, the IPO would sit near 20 times revenue. At $120 billion, the multiple falls to 16.7 times. At $190 billion to $200 billion, it falls to about 10.0 to 10.5 times. The risk is that those future numbers are doing a lot of work in today’s valuation.
Makes sense if
- annualized revenue reaches roughly $100 billion around the IPO and continues growing rapidly
- enterprise spending remains durable rather than shifting toward cheaper models
- compute costs grow slower than revenue and reported profitability converts into cash generation
Does not make sense if
- revenue stalls near the current $65 billion run rate
- training, inference and cloud costs absorb most of the operating gain
- regulation, safety pauses or competition make the $190 billion to $200 billion 2028 forecast unrealistic
Anthropic may be worth $965 billion today because private investors have already paid that price. A $2 trillion Anthropic is a different proposition. It asks investors to believe that revenue can catch the valuation before the growth curve, margins or AI spending cycle cool. The threshold is not mysterious. Around $97 billion of run-rate revenue would make $2 trillion roughly as aggressive on sales as the May funding round already was.
Answers to Common Questions
How much is Anthropic worth today?
Anthropic’s latest completed financing valued the company at $965 billion post-money in May 2026.
Is Anthropic really worth $2 trillion?
Not yet. About $2 trillion is a prospective IPO valuation under discussion, not a completed financing or public-market price.
How much revenue does Anthropic make?
Its annualized revenue run rate exceeded $65 billion by the end of July 2026. That figure annualizes the latest sales pace and is not the same as trailing twelve-month revenue.
Is Anthropic profitable?
The company has told investors it expects positive adjusted operating income for a second consecutive quarter. That measure excludes stock-based compensation, while the reported gross-margin figure also precedes revenue sharing and model-training costs.
Can investors buy Anthropic stock now?
Anthropic remains a private company until a public offering is completed. The planned IPO terms, valuation and timing can still change before shares begin public trading.
Disclosure: Educational content, not financial advice. Prices reflect public information as of the dates cited and can change. Confirm current rates, fees, taxes, and terms with official sources before purchasing. See our methodology and corrections policy.