
How Much Does an Allodial Title Cost?
Updated on | Written by Alec Pow
This article was researched using 11 sources. See our methodology and corrections policy.
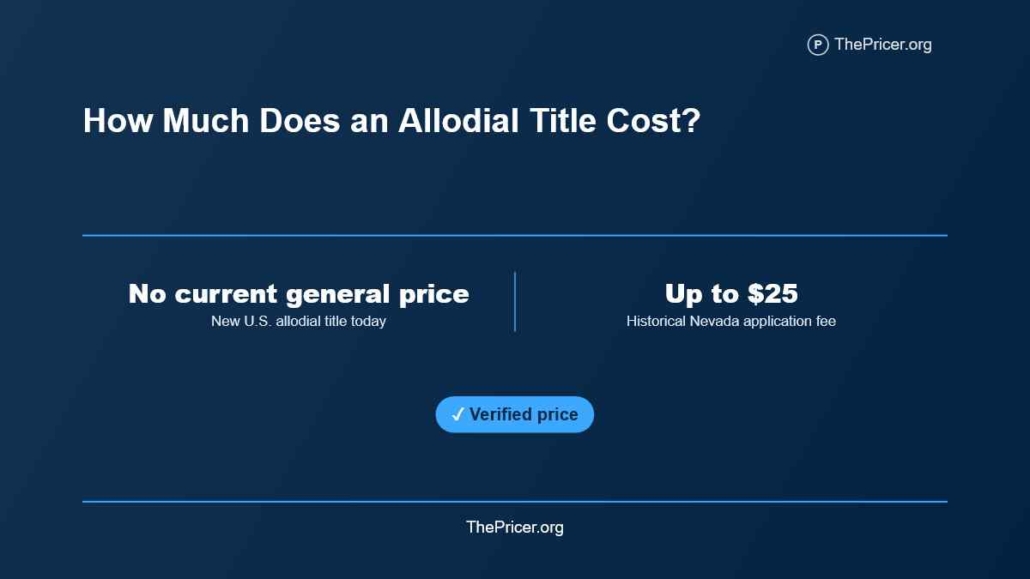
You cannot currently buy a new allodial title for an ordinary U.S. home through a general state program, so there is no current allodial-title price. Nevada once operated a statutory program, but new applications ended on June 13, 2005. The historical cost was not a flat filing fee or a simple percentage of the home’s value.
Under Nevada’s former system, a county could charge an application processing fee of no more than $25. The real cost was a much larger amount calculated by the State Treasurer so that the homeowner’s payment, plus investment earnings, could fund projected property taxes for a period equal to the life expectancy of the youngest titleholder. Homeowners could choose a lump sum or installments over no more than 10 years.
That distinction matters because a common reading of the old law turns its $5 per $100 of assessed value tax-rate assumption into a supposed purchase price. It was not. That rate was an input used to project the tax obligation that the trust account had to fund.
Article Highlights
Jump to sections
- There is no current general U.S. program we found that lets an ordinary homeowner purchase a new allodial title.
- Nevada stopped accepting new applications on June 13, 2005.
- The old Nevada application processing fee could be no more than $25 (at $30 per hour, earning that amount would take about 50 minutes, before taxes).
- The historical certificate cost was actuarially calculated, not simply 5% of the property’s assessed value.
- Nevada used a tax-rate assumption of $5 per $100 of assessed valuation, then projected life expectancy, investment income, and changes in assessed value.
- Existing Nevada allodial titles that were established before the cutoff remain governed by provisions still present in state law.
- A standard modern homeowner normally holds fee simple title and still remains subject to property tax, liens, zoning, eminent domain, and other public law.
How Much Does an Allodial Title Cost?
| Situation | Cost | What the number means |
|---|---|---|
| New U.S. allodial title today | No current general price | No current general state homeowner program comparable to Nevada’s former program |
| Historical Nevada application fee | Up to $25 (about 50 minutes at $30 per hour) | County processing fee permitted by statute |
| Historical Nevada tax-rate input | $5 per $100 of assessed value | Used to calculate projected tax liability, not the certificate price |
| Historical payment method | Lump sum or up to 10 years of installments | Treasurer calculated both alternatives |
| Modern fee simple title | No special allodial fee | Normal purchase, title, recording, financing, tax, and closing costs apply |
The current text of Nevada Revised Statutes Chapter 361 still states that applications had to be made no later than June 13, 2005. It also preserves the mechanics for certificates that were already established.
The 2005 Legislature made the shutdown explicit. Assembly Bill 570 prevented additional allodial titles and eliminated the former pathway for heirs to transfer and reestablish them.
What You’re Actually Buying
Allodial ownership is a historical property-law concept describing land held without a superior landlord. That idea is often presented online as though a homeowner can file special paperwork and become independent of property tax, foreclosure law, liens, or government authority.
That is not how ordinary American real-estate ownership works. The standard high-level private ownership estate is fee simple. Cornell’s Legal Information Institute describes fee simple as the greatest possible property interest in land, with fee simple absolute continuing indefinitely and passing through inheritance.
Even broad private ownership exists within laws governing taxation, zoning, eminent domain, mortgages, judgments, and other public and private claims. Nevada’s unusual program did not turn a homeowner into a sovereign landowner. It created a statutory certificate and a state-administered funding mechanism for future property taxes, with additional homestead protections under Nevada law.
How Nevada Actually Priced It
The old Nevada statute told the State Treasurer to calculate the amount needed to establish allodial title using a tax rate of $5 for each $100 (about 3.3 hours of work at $30 per hour) of assessed valuation. The Treasurer then had to determine a lump-sum option and an installment option of no more than 10 years.
The key sentence required the payment plus projected interest and other income to be enough to cover future property-tax liability for a period equal to the life expectancy of the youngest titleholder. Nevada’s administrative rules went further. The actuarial calculation under NAC 361.930 projected life expectancy, investment income, and changes in assessed valuation, including inflation and changes caused by construction, remodeling, or rebuilding.
This is why multiplying a property’s assessed value by 5% does not produce the certificate price. It produces one year’s modeled tax amount under the statutory rate assumption.
There is another easy mistake. Nevada does not normally assess real property at 100% of taxable value. The Nevada Department of Taxation explains that property is usually assessed at 35% of taxable value. Its current property-tax guide expresses the formula as taxable value × 35% = assessed value.
Take a hypothetical home with a taxable value of $500,000. At 35%, its assessed value would be $175,000. Applying the old allodial-program rate of $5 per $100 gives $8,750. That is the modeled annual tax input, not an $8,750 certificate.
If, purely for illustration, that $8,750 annual obligation stayed level for 30 years and the fund earned 4% annually, the present value of those payments would be about $151,305. The real Nevada calculation was more complicated because it projected changing assessed values, life expectancy, investment earnings, and other statutory assumptions. This example is finance math showing the scale, not a historical Treasurer quote.
Three Historical Cost Models
$300,000 taxable-value example: at Nevada’s 35% assessment level, assessed value would be $105,000. The old $5 per $100 rate produces a modeled annual tax of $5,250. A simplified 30-year present-value calculation at 4% is about $90,783.
$500,000 taxable-value example: assessed value would be $175,000, producing $8,750 in modeled annual taxes. The same simplified 30-year calculation gives about $151,305.
$750,000 taxable-value example: assessed value would be $262,500. At the statutory rate, modeled annual taxes equal $13,125. The simplified 30-year present value is about $226,958.
These numbers are deliberately not labeled as actual Nevada certificate prices. The official allodial program rules required the State Treasurer to pay future property taxes for qualified certificate holders and excluded special assessments, service charges, and fees that happened to appear on a property-tax bill. The program also applied to surface rights of the residential property rather than mineral rights.
Age could change the historical cost dramatically. Using the same hypothetical $8,750 annual payment and 4% illustration, funding 20 level years has a present value around $118,915, 30 years about $151,305, and 40 years about $173,187. A younger youngest titleholder meant a longer period that had to be funded.
What Existing Nevada Titles Do
Nevada still keeps allodial-title sections in its current statutes because certificates created before the cutoff can continue to have legal effects. After a certificate was issued, the county assessor stopped collecting ordinary property tax directly from the titleholder. Instead, the State Treasurer paid the tax from that property’s subaccount in the Allodial Title Trust Account.
The title was not permanent regardless of what happened to the property. Current NRS 361.915 requires relinquishment upon events such as sale, lease, or other transfer, when the last surviving titleholder stops occupying the dwelling for the statutory period, or when the home is converted away from an owner-occupied single-family dwelling.
Nevada also gave these titles unusually strong homestead treatment. Current NRS 115.010 limits the ordinary Nevada homestead exemption to $605,000 of equity, while a qualifying allodial title that has not been relinquished extends the exemption to all equity in the dwelling, appurtenances, and land. The statute contains exceptions and expressly states that allodial title does not block specified forfeiture laws.
That is much more specific than saying the owner became immune from government action. The protection existed because Nevada statutes created it, and those same statutes defined its limits.
What Homeowners Pay Today
 For a normal home purchase today, the relevant ownership interest is usually fee simple rather than allodial title. The costs are ordinary transaction expenses such as title services, recording, lender fees if financing is used, appraisal, taxes, insurance prepayments, and any transfer charges imposed by the jurisdiction.
The CFPB explains that title service fees can include the title search, lender’s title-insurance premium, and other services involved in issuing the policy. An owner’s policy is a separate protection for the homeowner and is usually a one-time premium.
Industry data published by the American Land Title Association put the median combined cost of title insurance and settlement services at 0.67% of the purchase price. On a $500,000 purchase, that benchmark equals about $3,350. The ALTA cost analysis notes that title pricing varies by state regulation and transaction structure.
Those costs buy title examination, settlement work, and insurance protection. They do not buy tax-free or sovereign ownership. The CFPB also says consumers can often shop for title and settlement services, with research suggesting savings of as much as $500 on title services in some transactions.
If your real goal is reducing ownership costs, legitimate routes are much more ordinary: claim a homestead or other property-tax exemption for which you qualify, compare title and settlement providers when shopping is permitted, challenge an incorrect assessment through the lawful local process, and compare financing costs carefully. None of those changes fee simple ownership into allodial title.
For related ownership expenses, see our guides to Home Title Lock costs, the cost to subdivide land, and the cost of an acre of land.
Allodial Car Titles
Real-property estates and motor-vehicle certificates of title are different legal systems. Paying off a car loan can remove the lender’s lien, but it does not turn the vehicle into allodial property.
State DMVs issue titles under motor-vehicle statutes and maintain records of owners, liens, transfers, salvage status, and registration requirements. For one current example, the Nevada DMV title system lists ordinary certificates of title, lien releases, ownership transfers, duplicate titles, and related fees. It does not offer an allodial-title category.
We found no official DMV pathway that converts a vehicle into an “allodial” asset exempt from normal registration, tax, lien, or traffic laws. A private document carrying that label should not be confused with a state-issued vehicle title.
What to Pay For Instead
Makes sense if:
- You are paying a licensed title, escrow, settlement, or legal professional for a real service connected with a property transaction.
- You are purchasing title insurance and understand whether it protects the lender, the owner, or both.
- You are filing for a real homestead or tax exemption authorized by your state or county.
- You are paying a county recording charge shown on an official fee schedule.
Does not make sense if:
- Someone promises a new “allodial title” that permanently ends property taxes in any state without pointing to a current state statute and agency process.
- A seller calculates the price simply as 5% of your home’s value and calls that the Nevada formula.
- A private service claims a document can make your car exempt from DMV registration, liens, or state law.
- The pitch says paying off your mortgage automatically converts fee simple ownership into allodial ownership.
What We Checked
- Checked the current Nevada statutes and confirmed that new allodial-title applications had to be filed no later than June 13, 2005.
- Confirmed that the old county application processing fee could not exceed $25.
- Verified that $5 per $100 of assessed value was an input to the Treasurer’s tax-funding calculation rather than the certificate price itself.
- Cross-referenced Nevada’s assessment system and confirmed that assessed value is usually 35% of taxable value.
- Verified that the actuarial rules projected life expectancy, investment income, inflation, and changes in assessed value.
- Checked current Nevada homestead law and confirmed that surviving allodial titles receive special statutory treatment but are not unlimited immunity from every lien, forfeiture, or government power.
Answers to Common Questions
Can I buy an allodial title in the United States in 2026?
We found no current general state program comparable to Nevada’s former homeowner program. Nevada stopped accepting new applications on June 13, 2005.
How much did a Nevada allodial title cost?
There was no universal price. The county could charge up to $25 to process the application, while the State Treasurer separately calculated a much larger lump sum or installment amount designed to fund projected property taxes for the youngest titleholder’s life expectancy.
Was the Nevada price 5% of the property’s assessed value?
No. The old law used $5 per $100, equal to 5% of assessed value, as a tax-rate assumption. The Treasurer then calculated how much money had to be funded so that the principal and projected earnings could pay future taxes over the required period.
Does paying off a mortgage give me allodial title?
No. Paying off the mortgage removes that lender’s security interest when the lien is properly released. It does not change ordinary fee simple ownership into allodial ownership or end property-tax obligations.
Can an allodial title stop eminent domain or every lien?
No blanket claim like that is supported by Nevada’s statute. The former program created specific tax-payment and homestead effects, while state law retained exceptions and other government powers.
Can I get an allodial title for a car?
We found no official state DMV process offering an allodial vehicle title. Motor-vehicle titles are statutory ownership records and remain subject to registration, tax, lien, and other state requirements.
Disclosure: Educational content, not financial advice. Prices reflect public information as of the dates cited and can change. Confirm current rates, fees, taxes, and terms with official sources before purchasing. See our methodology and corrections policy.