
How Much Does a Safe Deposit Box Cost?
Updated on | Written by Alec Pow
This article was researched using 14 sources. See our methodology and corrections policy.
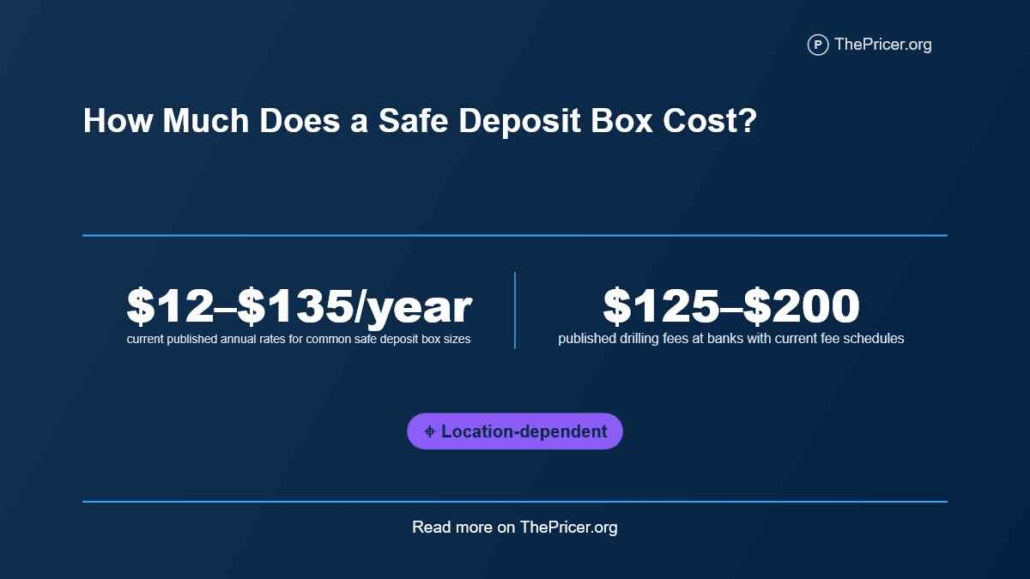
A safe deposit box can cost from about $12 to $45 per year for a small box in current published bank schedules, while a 3-by-10-inch box can run about $20 to $100 per year. Published 10-by-10-inch rates reviewed reach about $70 to $135 per year, and larger vault compartments can reach roughly $500 per year. These figures are observed rates, not a national average.
Price depends on box size, branch location, bank relationship, payment method, and availability. Major banks such as Bank of America and Wells Fargo often require a branch inquiry for the actual annual rent. Extra charges for late payment, lost keys, or drilling can exceed the annual rent by a wide margin.
Article Highlights
Jump to sections
- Published small-box rates reviewed start at $12 (at $30 per hour, earning that amount would take about 24 minutes, before taxes) per year and reach about $45 per year.
- Current 3-by-10-inch rates reviewed range from $20 to $100 per year.
- A 10-by-10-inch box can cost about $50 to $135 per year depending on bank relationship and payment method.
- Drilling charges can reach $125 to $200 at banks with published fees.
- Safe deposit box contents are not insured by the FDIC.
- Branch inventory can matter as much as price because many banks do not guarantee that a chosen size is available.
How Much Does a Safe Deposit Box Cost?
Published 2026 schedules show a much wider spread than the old idea that every small box costs roughly the same. The current Florida safe deposit schedule, New York safe deposit schedule, current Unico box rates, and current St. Johns rates provide direct bank examples.
| Bank and scope | Box size | Current annual fee |
|---|---|---|
| Unico Bank | 3 x 5 | $12 (about 24 minutes at $30 per hour) |
| Popular Bank Florida | 3 x 10 | $55 |
| Popular Bank New York | 3 x 10 | $100 |
| Popular Bank Florida | 10 x 10 | $130 |
| St. Johns Bank, 10 x 10 | Relationship and payment dependent | $50 to $135 |
| St. Johns Bank, large vault compartment | 6+ cubic feet | $460 to $510 |
The low end is real, but it is not universally available. Unico requires automatic payment of the annual rental fee and says sizes vary by location. St. Johns changes the rate based on customer status and whether the bill is automatically debited. The same nominal box size can have a very different price under another branch network. A quoted rate should also identify whether taxes are included and whether automatic debit is required. Check that before signing.
Size, Location, and Account Status
Box size is the obvious price driver, but geography can be just as important. Popular Bank charges $55 (about 1.8 hours of work at $30 per hour) per year for a 3-by-10-inch box in its Florida schedule and $100 per year for the same nominal size in New York. The difference is $45 per year. Dividing that difference by the Florida rate shows the New York fee is about 82% higher in this matched comparison.
That comparison is useful because the bank, billing period, and box dimensions are held constant. It does not prove that New York boxes are 82% higher across the entire market. It shows how far location alone can move a published rate inside one bank.
Account relationship can create an equally large swing. St. Johns lists a 10-by-10 box at $135 per year for non-customers, $100 for customers using automatic debit, and $50 for Premier Checking customers using automatic debit. If current rates stayed unchanged for five years, those totals would be $675, $500, and $250. The modeled difference between the non-customer and lowest listed relationship rate is $425 over five years.
Ask whether the quoted rent requires a checking account, automatic debit, a relationship tier, or a specific branch. A slightly cheaper box at a distant branch can also lose its advantage if access requires repeated travel during banking hours.
Which Banks Still Offer Boxes?
Availability is now part of the price question. Bank of America says most financial centers offer boxes, but it directs customers to the local financial center for availability and specific fees. Wells Fargo also says safe deposit boxes can be rented at most of its locations, with annual rent varying by box size and local availability.
This means a national price chart can be less useful than it appears. A bank may still operate safe deposit facilities while a nearby branch has no vacant boxes in the size you want. Another branch may have space but use a different local rate. Large banks may publish the rules for the service without publishing one nationwide rental price.
Availability can be the bottleneck. Before comparing a $35 small-box rate with a $50 rate elsewhere, confirm that the cheaper size can actually be rented. Ask about the annual price, available dimensions, account requirement, automatic payment rules, branch access hours, joint lessees, and what happens if that vault location closes.
A safe deposit box is also very different from a P.O. box rental. One stores valuables inside a bank vault, while the other receives mail. A storage unit rental is another separate service built for much larger physical property.
Fees Beyond the Annual Rent
Annual rent can be the smallest number on a bad-year bill. Bank of America’s published miscellaneous fee disclosure lists safe deposit box rent as variable by size, a $150 drilling fee, and a $10 late-payment fee after 30 days. Popular Bank’s Florida schedule lists a $125 drilling fee, $15 lost-key fee, and $8 late fee.
Those fees change the economics of a cheap box. Popular Bank Florida charges $55 per year for a 3-by-10 box. Its $125 drill fee equals about 2.3 years of that base rent. Avoiding one preventable lock event can matter more than finding a branch that saves $10 a year.
Consider a five-year scenario using that same Florida 3-by-10 rate. Assume the published annual rate remains unchanged, the renter incurs one drill fee, and one annual payment becomes late enough to trigger the listed fee.
- Five years of rent at $55 per year equals $275.
- One drilling charge adds $125.
- One late fee adds $8.
- The modeled five-year total becomes $408.
The extra two events add $133, raising the modeled five-year outlay by about 48%. This is an illustrative scenario, not a claim that renters normally incur these charges. Read the local lease before assuming a lost key, drilling event, replacement lock, or late payment will be handled the same way at every bank.
FDIC Coverage and Private Insurance
The bank may be FDIC-insured, but the property inside the box is not a bank deposit. The FDIC insurance guidance states that safe deposit boxes and their contents are not insured by the FDIC. A bank failure also does not convert jewelry, documents, currency, or collectibles in the vault into an insured deposit.
This distinction matters when the stored property has high replacement value. A bank contract may offer limited protection under narrow circumstances, but a renter should not assume the annual box fee purchases insurance for the contents. Homeowners or renters insurance may offer some coverage, and valuable items may need separate scheduling, appraisals, limits, or deductibles based on the insurer’s terms.
The old rule of budgeting a fixed insurance charge for every $1,000 of property is too crude. Insurance pricing depends on what is stored, stated value, location, policy structure, deductible, and the carrier. Get a quote for the actual property rather than applying one universal rate.
Keep an inventory and proof of ownership somewhere outside the box. Photos, receipts, appraisals, serial numbers, and copies of key documents can support an insurance claim or estate process if the originals become inaccessible.
What Belongs in the Box
A safe deposit box works best for valuables and documents that need secure storage but do not need instant access. Chase’s safe deposit storage guidance lists items such as birth certificates, marriage licenses, property deeds, car titles, collectible coins, family jewelry, heirlooms, photos, hard drives, and copies of estate documents as possible candidates.
Emergency-use documents are a different matter. Passports, medical directives, and material needed when the branch is closed may be difficult to retrieve at the exact time they are needed. Cash also loses two advantages inside a box. It is not covered by FDIC deposit insurance and earns no interest.
The FDIC also advises checking state-law requirements with an attorney before placing an original will in a safe deposit box. Access after death depends on state law, the lease, joint ownership, authorized access, and estate procedures. A copy in the box and a properly controlled original elsewhere may fit some estate plans better, but legal advice should match the renter’s state and documents.
Each bank sets prohibited-content rules. Chase’s current box lease restrictions prohibit dangerous or illegal items, weapons, drugs, perishables, liquids, corrosive materials, pressurized materials, and ordinary money unless it is collectible. Read your own lease because another bank can use different terms.
Bank Box vs Home Safe
A bank vault box trades immediate access for off-site security. A home safe gives access at any hour and keeps documents close, but it also sits on property that a burglar can enter. The FDIC home-safe comparison notes that a home safe is not a direct replacement for a bank box and that neither option is completely protected from theft, fire, flood, or other damage.
The cost structure is different too. A bank box creates recurring annual rent and possible service fees. A home safe shifts spending toward the initial purchase, installation or anchoring, maintenance, and any insurance consequences. Comparing a small fire chest with a bank vault box is not a matched security comparison because burglary resistance, fire rating, water resistance, anchoring, and access are different.
Time matters as well. A box that costs $55 per year would total $550 over ten years if the rate never changed. A $130 annual box would total $1,300 under the same assumption. Those figures are not forecasts because banks can change renewal prices. They show the recurring-cost scale a renter should compare with a suitable home-storage option.
Mail storage is a separate decision. Someone who needs a secure address for documents arriving by mail should compare UPS mailbox rental costs or USPS options rather than treating a safe deposit box as a mail service.
Choosing the Right Box
Start with the property, not the largest box available. Documents, small jewelry cases, backup drives, and collectibles can fit very different dimensions. Ask the branch for internal measurements because the advertised face dimensions do not tell you every usable dimension or tray layout. Check whether the box requires an existing account and whether automatic payment changes the annual fee.
Then compare the entire ownership period. A low annual rent can be outweighed by travel, account requirements, inconvenient access, or service charges. A relationship discount can be valuable when the checking account already fits your needs. Opening an unwanted account solely to save on box rent can create a separate banking cost.
Makes sense if
- You need off-site storage for valuables or documents that do not require immediate access.
- The branch has the size you need at a published or quoted annual price you accept.
- Your insurance plan covers valuable contents at the level you need.
- You can keep backup records and emergency documents somewhere accessible.
Does not make sense if
- You need the stored item outside branch hours.
- You plan to keep ordinary cash there instead of an insured deposit account.
- The only available branch is inconvenient enough to limit practical access.
- You assume the bank’s FDIC status automatically insures the box contents.
The best quote is the one with a usable box, clear access rules, manageable renewal terms, and fees you have actually reviewed. Annual rent alone is too narrow a comparison.
Answers to Common Questions
How much does a small safe deposit box cost?
Current published examples reviewed start near $12 per year and reach about $45 per year for small sizes, with branch and account rules affecting the rate.
How much does a 10-by-10 safe deposit box cost?
Current published examples reviewed run from about $50 to $135 per year, depending on the bank, customer relationship, and payment method.
Are safe deposit box contents FDIC-insured?
No. FDIC deposit insurance does not cover a safe deposit box or the property stored inside it.
Can I keep cash in a safe deposit box?
It is a poor fit for ordinary cash because the money is not FDIC-insured and earns no interest. Some bank agreements also restrict currency storage.
What happens if I lose the key?
The bank may charge for a replacement key, lock work, or drilling. Published drilling fees reviewed range from no charge at one bank to $200 at another.
Disclosure: Educational content, not financial advice. Prices reflect public information as of the dates cited and can change. Confirm current rates, fees, taxes, and terms with official sources before purchasing. See our methodology and corrections policy.